

The minimum wage in Poland in 2027 will be PLN 4,950 gross per month from 1 January 2027, up PLN 144 (3.0%) from 2026. The statutory minimum hourly rate for covered civil-law contracts will be PLN 32.30. For a typical full-time employee, this translates into approximately PLN 3,703.93 net and PLN 5,963.77 in monthly employer payroll costs, subject to individual circumstances. These are the figures employers should use as a starting point for 2027 payroll budgets. Legal status: October 2026.
Key Takeaways
- Monthly minimum: PLN 4,950 gross from 1 January 2027.
- Increase: PLN 144, or 3.0%, compared with 2026.
- Minimum hourly rate for covered service and mandate contracts: PLN 32.30 gross.
- Illustrative employee take-home pay: PLN 3,703.93 monthly.
- Illustrative employer cost: PLN 5,963.77 monthly, excluding PPK and other employment costs.
Source: Council of Ministers Regulation of 14 September 2026 (Journal of Laws 2026, item 1213).
Minimum Wage in Poland 2027 at a Glance
| Item | 2026 | 2027 | Change |
|---|---|---|---|
| Monthly gross wage | PLN 4,806 | PLN 4,950 | +PLN 144 (+3.0%) |
| Minimum hourly rate (covered civil-law contracts) | PLN 31.40 | PLN 32.30 | +PLN 0.90 |
| Illustrative monthly net | Approx. PLN 3,606 | PLN 3,703.93 | Approx. +PLN 98 |
| Illustrative monthly employer cost | PLN 5,790.26 | PLN 5,963.77 | +PLN 173.51 |
The figures for net pay and employer cost are simulations, not statutory fixed amounts. Euro equivalents fluctuate with exchange rates and should be calculated using the NBP rate on the date of publication.
How the 2027 Minimum Wage Was Set
The government presented its proposal to the Social Dialogue Council in June 2026. The parties did not agree on a common figure; trade unions sought at least PLN 5,200 while employers supported the government’s level. The Council of Ministers therefore adopted the final rates by regulation on 14 September 2026 under the Act of 10 October 2002 on Minimum Remuneration for Work. The regulation was published on 15 September and takes effect on 1 January 2027. Government background.
Minimum Wage Net: How Much Does the Employee Receive?
Assuming an ordinary employment contract, employee pension/disability/sickness contributions, standard PLN 250 tax-deductible costs, a valid PIT-2 allowing a PLN 300 monthly tax reduction, no PPK, and no special relief, the calculation is:
| Component | Amount (PLN) |
|---|---|
| Gross monthly wage | 4,950.00 |
| Employee pension contribution (9.76%) | 483.12 |
| Employee disability contribution (1.5%) | 74.25 |
| Employee sickness contribution (2.45%) | 121.28 |
| Health contribution (9% of applicable base) | 384.42 |
| PIT advance (illustrative) | 183.00 |
| Net monthly pay | 3,703.93 |
Without a PIT-2 declaration, with PPK participation, or under the under-26 income tax relief, take-home pay may differ. See our guide to the PIT-2 declaration and personal income tax in Poland.
Employer Cost of a Minimum-Wage Employee in 2027
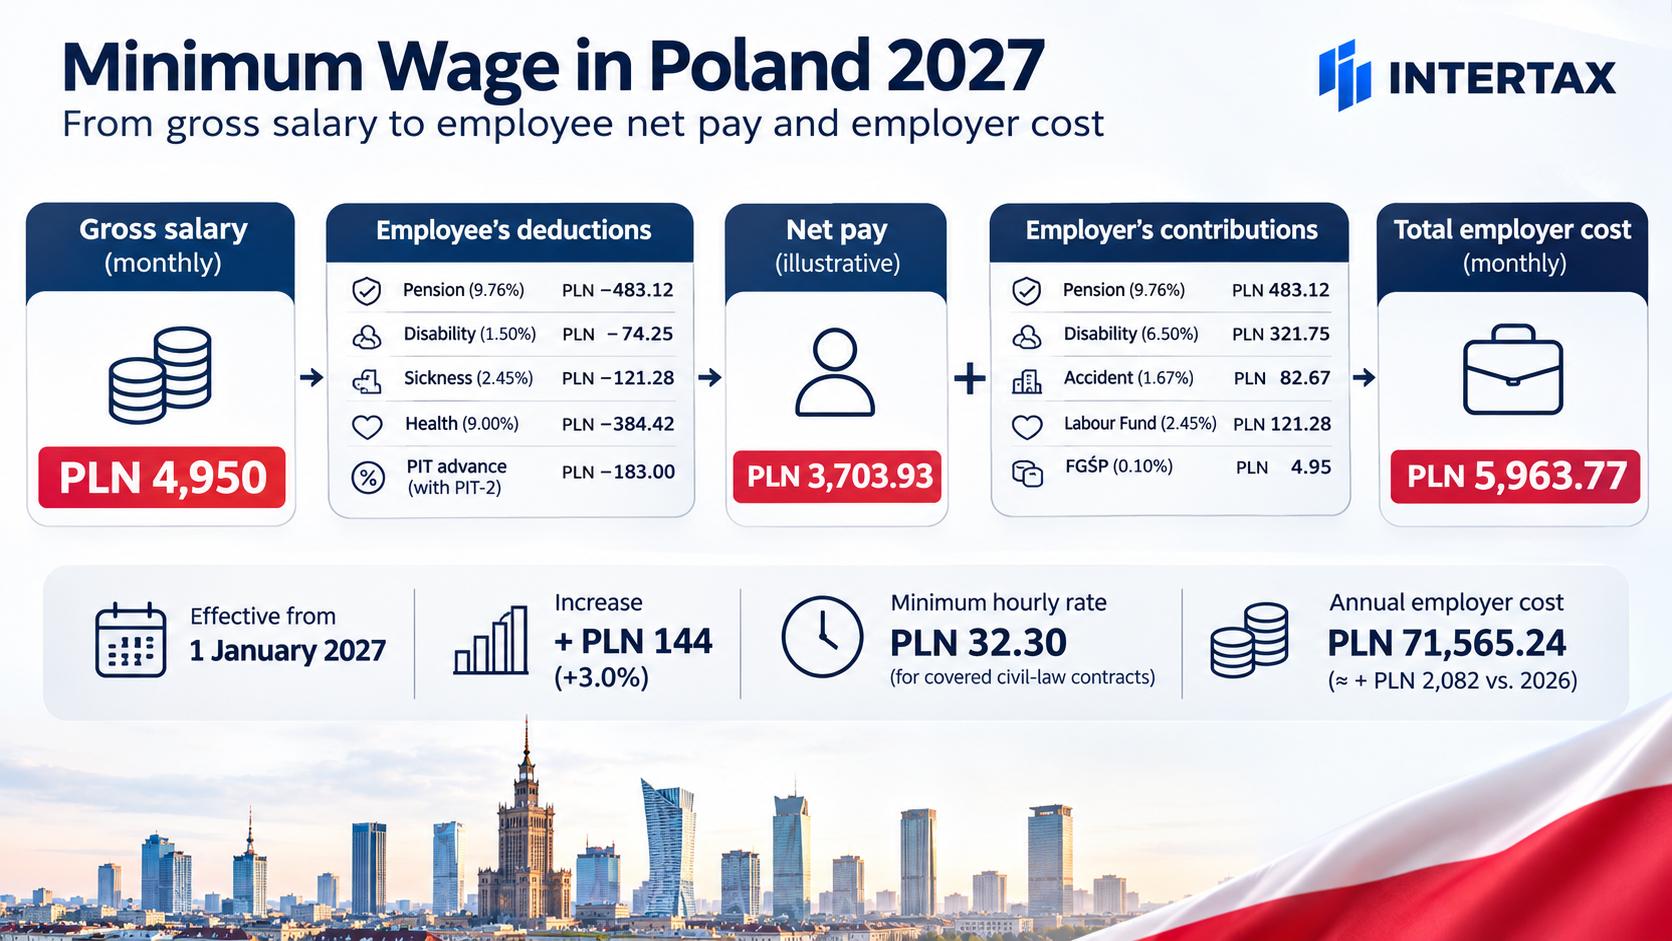
Gross pay is not the employer’s total payroll cost. The following example uses an accident insurance rate of 1.67%, which varies by employer.
| Employer cost component | Monthly PLN |
|---|---|
| Gross wage | 4,950.00 |
| Pension (9.76%) | 483.12 |
| Disability (6.5%) | 321.75 |
| Accident insurance (illustrative 1.67%) | 82.67 |
| Labour Fund / Solidarity Fund (2.45%) | 121.28 |
| FGŚP (0.10%) | 4.95 |
| Total monthly cost | 5,963.77 |
Based on individually rounded contribution amounts, the total is PLN 5,963.77 per month or PLN 71,565.24 per year. At an equivalent 2026 contribution profile, the cost is approximately PLN 5,790.26 monthly; the annual increase is approximately PLN 2,082 per employee. Employers may also incur PPK contributions (normally 1.5% of remuneration, or PLN 74.25 monthly here), occupational health and safety, training, equipment and other costs. Read more about the true cost of hiring an employee in Poland and PPK employee capital plans.
Payroll budgeting 2027
Planning payroll costs for 2027 in Poland?
INTERTAX payroll teams can help international businesses budget employer costs and update payroll for the new minimum wage.
Minimum Hourly Rate for Contracts of Mandate: PLN 32.30
From 1 January 2027, the statutory minimum hourly rate for covered mandate and service contracts will be PLN 32.30 gross. It may apply to individuals and certain sole traders performing services personally, subject to statutory exceptions, including specific commission-only arrangements. This rate must not be confused with an hourly equivalent of the monthly minimum for employment contracts: the latter depends on working hours in a particular month. See the rules for employment contracts in Poland.
What Counts Towards the Minimum Wage (and What Does Not)
Under the existing statutory framework, the comparison generally takes account of basic salary and eligible wage components, including qualifying bonuses. Excluded components include overtime pay, night-work allowance, jubilee awards, retirement/disability severance, seniority allowance and special-condition work allowance. Employers must check the full current list in Article 6(5) of the Minimum Remuneration Act. Consequently, basic salary alone need not always equal PLN 4,950 where other qualifying components bring total remuneration to the statutory threshold. This position should be reassessed if the pending legislative reform changes the composition rules.
Part-Time Employees and New Hires
For part-time employment, the statutory monthly minimum is proportionate to contracted working time: for example, a half-time employee’s 2027 minimum is PLN 2,475 gross. A partial first month requires the appropriate calculation for the period worked. The old 80% rule for a worker’s first year has not applied since 2017.
What Else Changes When the Minimum Wage Goes Up?
| Linked item | Calculation or impact in 2027 |
|---|---|
| Night-work allowance | 20% of the hourly rate derived from PLN 4,950; varies with monthly working hours |
| Downtime remuneration | Statutory floor linked to minimum pay, subject to working-time proportion |
| Collective redundancy severance cap | 15 × PLN 4,950 = PLN 74,250 |
| Minimum compensation for unlawful unequal treatment | At least PLN 4,950, where statutory minimum-wage reference applies |
| Protected amount from wage deductions | Calculated using the applicable net minimum and deduction category |
| Preferential social insurance base for qualifying new businesses | 30% × PLN 4,950 = PLN 1,485 |
| Health contribution for entrepreneurs | Depends on the taxation method and relevant contribution year; do not assume one universal PLN amount |
For night work, the precise allowance changes from month to month with working-time norms. HR teams should update payroll rules, not just the base-salary field. See our guide to working time in Poland.
Updating night-work allowances and payroll thresholds for 2027? Check your payroll settings with INTERTAX.
Contact usMinimum Wage in Poland: History 2013–2027
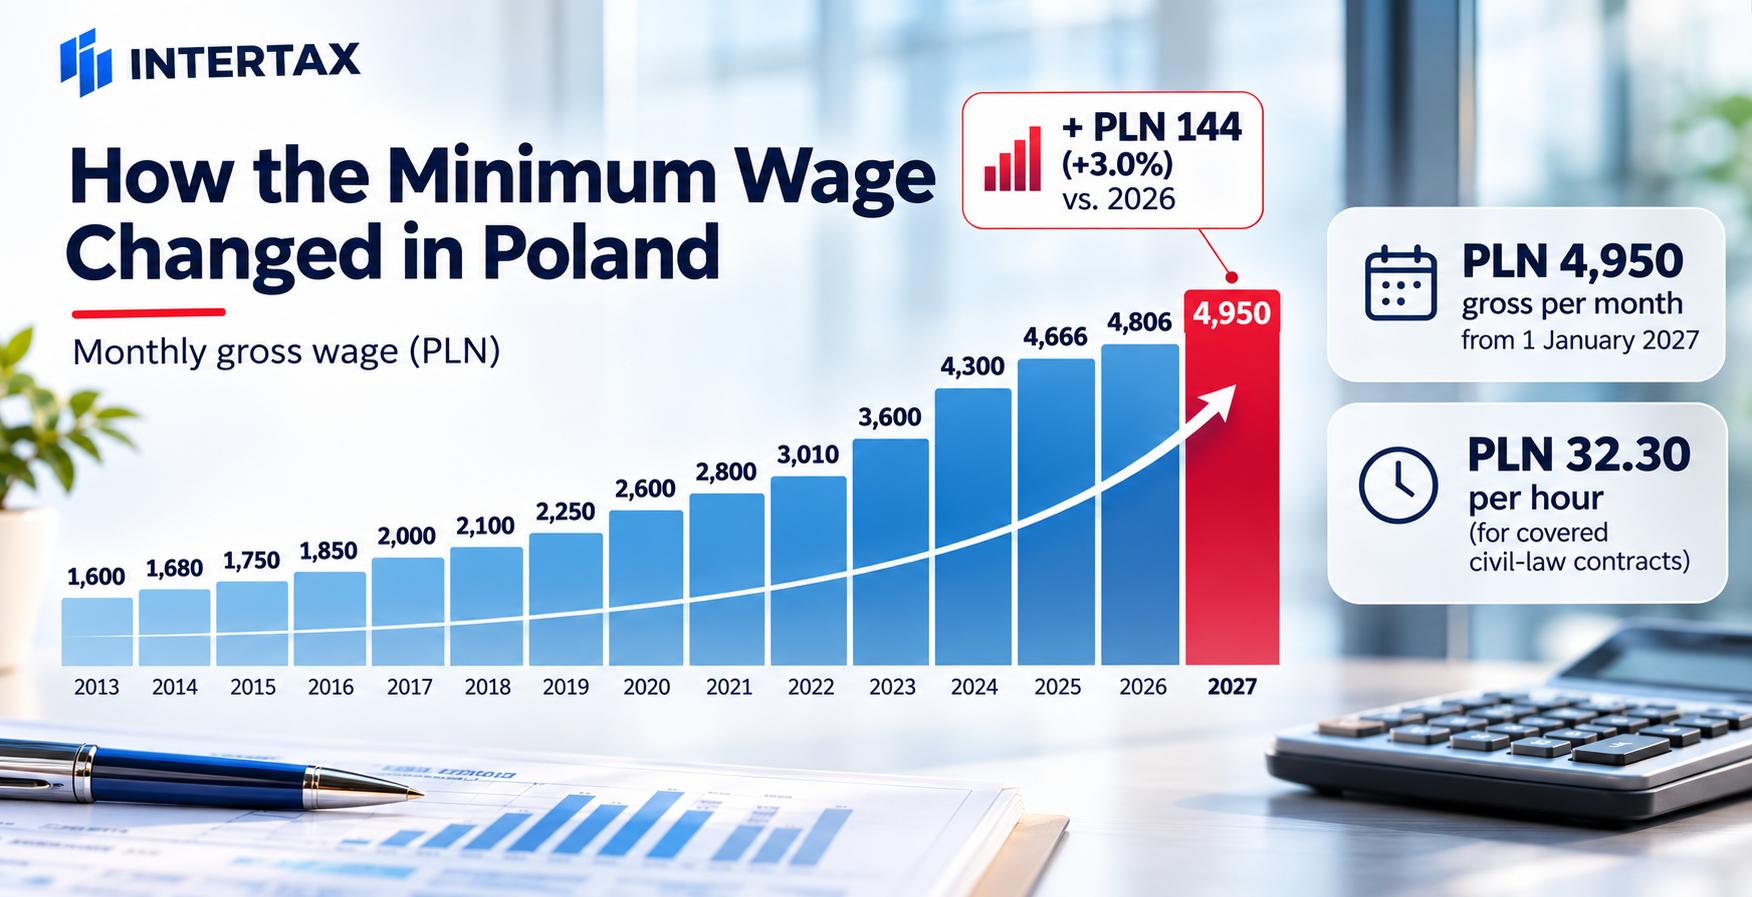
| Year | Monthly gross PLN | Minimum hourly rate PLN |
|---|---|---|
| 2013 | 1,600 | Not yet statutory |
| 2014 | 1,680 | Not yet statutory |
| 2015 | 1,750 | Not yet statutory |
| 2016 | 1,850 | Not yet statutory |
| 2017 | 2,000 | 13.00 |
| 2018 | 2,100 | 13.70 |
| 2019 | 2,250 | 14.70 |
| 2020 | 2,600 | 17.00 |
| 2021 | 2,800 | 18.30 |
| 2022 | 3,010 | 19.70 |
| 2023 Jan / Jul | 3,490 / 3,600 | 22.80 / 23.50 |
| 2024 Jan / Jul | 4,242 / 4,300 | 27.70 / 28.10 |
| 2025 | 4,666 | 30.50 |
| 2026 | 4,806 | 31.40 |
| 2027 | 4,950 | 32.30 |
The 2027 increase is modest relative to several recent years.
Minimum Wage in Poland vs Other EU Countries
Cross-country comparisons should use the latest harmonised Eurostat minimum wage statistics, which convert national rates into euros and purchasing-power standards. Rankings change with exchange rates and reporting periods; a Polish PLN wage cannot be compared directly with another country’s euro-denominated wage without specifying the date and measure.
Employer Checklist Before 1 January 2027
- Identify employees whose qualifying remuneration is below or close to PLN 4,950.
- Review part-time salaries and covered mandate-contract hourly rates.
- Update night-work allowances and payroll-dependent thresholds.
- Reforecast employer social contributions and PPK costs.
- Prepare contract amendments where fixed contractual pay requires changing.
- Inform managers and employees of the revised rates and effective date.
International businesses can ask INTERTAX for support with payroll services in Poland, budgeting and local compliance. Contact our team.
Frequently Asked Questions
What is the minimum wage in Poland in 2027?
From 1 January 2027, the minimum monthly wage for a full-time employee will be PLN 4,950 gross. This is PLN 144 more than the PLN 4,806 applicable in 2026. The figure is legally established by the Council of Ministers Regulation of 14 September 2026.
What is the minimum hourly rate in Poland in 2027?
The statutory hourly minimum for covered mandate and service contracts will be PLN 32.30 gross from 1 January 2027. This is not a universal hourly rate for employment contracts. The hourly equivalent of a full-time employee’s monthly wage depends on the working-time schedule in the relevant month.
How much is the minimum wage in Poland after tax?
In a standard illustrative calculation, PLN 4,950 gross gives PLN 3,703.93 net per month. This assumes standard deductible costs, an applicable PIT-2 monthly reduction, ordinary employee social and health contributions and no PPK. The actual result can differ according to the employee’s tax and insurance circumstances.
How much does a minimum-wage employee cost an employer in Poland?
At PLN 4,950 gross, the illustrative monthly employer cost is PLN 5,963.77, using a 1.67% accident insurance rate and standard employer contributions. This excludes employer PPK, benefits and other operating costs. The employer’s accident rate and certain contribution exemptions may change the result.
Does basic salary have to equal the minimum wage?
Under the current rules, not necessarily. Some qualifying bonuses and other remuneration components may count toward the minimum, so the basic salary can be lower if the total eligible pay reaches PLN 4,950. Statutory exclusions and any subsequent legislative changes must be checked before setting salary structures.
Does the minimum wage apply to part-time employees?
Yes. The statutory monthly amount is adjusted proportionately to the employee’s contracted working time. For example, half-time employment generally means a minimum of PLN 2,475 gross per month in 2027. Payroll teams must also account correctly for partial months, absences and variable pay.
How often does the minimum wage change in Poland?
The government sets statutory minimum wage rates for the relevant calendar year under the applicable legal procedure. Some years have one rate and others, including 2023 and 2024, had increases during the year. For 2027, the published regulation provides rates effective from 1 January.
Payroll and HR Support for Employers in Poland
INTERTAX supports employers with payroll services in Poland and HR administration, including minimum-wage salary reviews, updates to payroll-dependent allowances and employer cost budgeting. If your team needs help, contact INTERTAX to discuss the employment arrangements and documents involved.